Support Guide
Motorhome Insurance & Breakdown Guide
Practical ways to compare motorhome insurance and breakdown cover, reduce costs, and protect your Roller Team motorhome.
Overview
Get better cover prices
How to Get the Best Prices on Motorhome Insurance & Breakdown Cover
Owning a Roller Team motorhome is all about freedom, adventure, and making memories on the open road. However, keeping running costs down—specifically when it comes to annual insurance and breakdown cover—is essential to keeping your hobby affordable.
Over the years, we’ve picked up several tried-and-tested tips that can drastically slash your quotes without sacrificing the quality of your cover. Here is how you can secure the best possible deal.
With these few little tips and a bit of time you could find that it is your best spent time this year.
1. Shop 28 days early
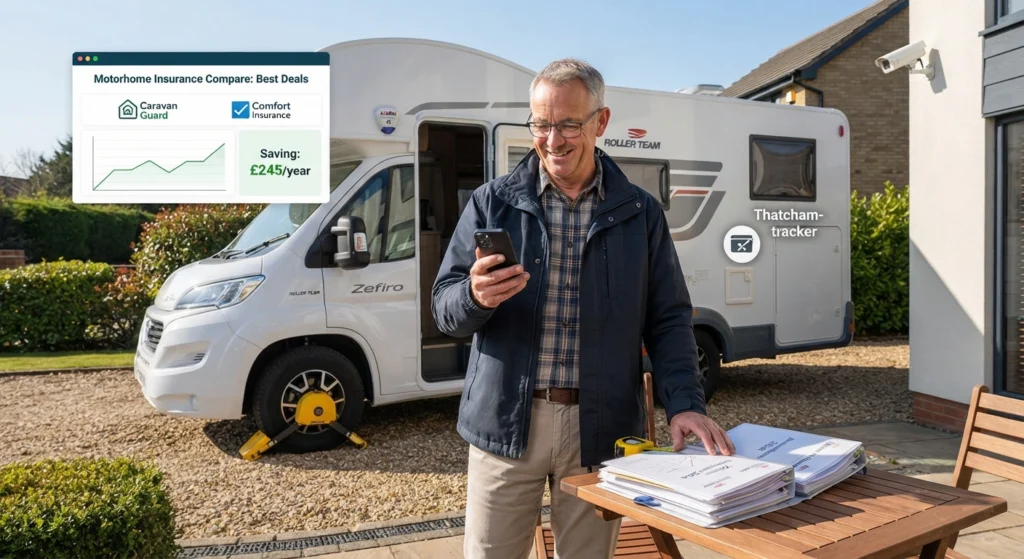
The Sweet Spot: Shop Around 28 Days Before Renewal
Leaving your insurance renewal to the absolute last minute is one of the most expensive mistakes you can make. Insurers often view people who buy policies on the day of renewal as higher risk.
The Strategy: Aim to get your quotes around 28 days before your current policy expires. Statistically, this is the “sweet spot” where insurers offer their most competitive introductory rates.
2. Use specialist insurers
Look Beyond Standard Sites – Use Specialist Motorhome Insurers
Standard comparison websites often struggle to price leisure vehicles accurately, sometimes treating them like ordinary cars or commercial vans.
The Strategy: Check quotes directly with specialist leisure vehicle brokers and underwriters. Big names trusted heavily within the motorhome community include:
Renowned for dedicated motorhome packages (often backed by major underwriters like Aviva) offering great policy benefits like EU cover and high personal effects limits.
Highly rated for competitive pricing and comprehensive leisure-specific cover.
Excellent for bespoke modifications, imports, or unique setups.
Shield Total Insurance & Peter Best Insurance
Both offer robust specialist policies built specifically for motorhomes and campervans.
3. Separate breakdown cover
Separate Your Insurance and Breakdown Cover (And Check Your Bank!)
Many insurance providers try to bundle breakdown cover into your main policy as a pricey add-on.
The Strategy: Buy your motorhome insurance and breakdown cover separately to open up a much wider pool of options.
The Bank Account Loophole: Some premium packaged bank accounts offer “free” or included breakdown cover as a perk.
Nationwide FlexPlus Breakdown Cover
Crucial Warning
If you go this route, always check the small print. Standard bank breakdown policies are built for ordinary cars and will often reject or fail to cover vehicles over 3.5 tonnes, or those exceeding specific length and height limits. Make sure your vehicle’s exact weight and dimensions are fully accommodated.
4. Keep details accurate
Be Precise with Your Annual Mileage
It’s easy to overestimate how many miles you’ll tour in a year “just in case,” but insurers charge you based on risk exposure.
The Strategy: Calculate realistically how many miles you actually intend to do. If you only plan on 5,000 miles a year, make sure your policy reflects that rather than defaulting to a generic 10,000-mile bracket.
5. Add additional drivers
Add a Named Driver (Especially a Spouse or Partner)
It sounds counterintuitive that adding another person to a policy could lower the price, but insurers love stability.
The Strategy: Including your wife or partner as a second driver often reduces the quoted price. This is especially true if you both have clean driving licences and a similar amount of No Claims Bonus (NCB), signalling a lower-risk, family-oriented profile.
6. Value it right
Don’t Overvalue Your Motorhome
When insuring a motorhome, you need the correct market or replacement value, but guessing too high inflates your premium.
The Strategy: Check the current market value of your specific Roller Team model. Over-valuing means paying higher premiums for a pay-out you’ll never realistically need. Conversely, aim for what it would genuinely cost to replace it with an equivalent model tomorrow.
7. Secure it
Boost Your Security (And Tell Your Insurer!)
Motorhomes are high-value targets, and insurers reward physical security measures that deter thieves.
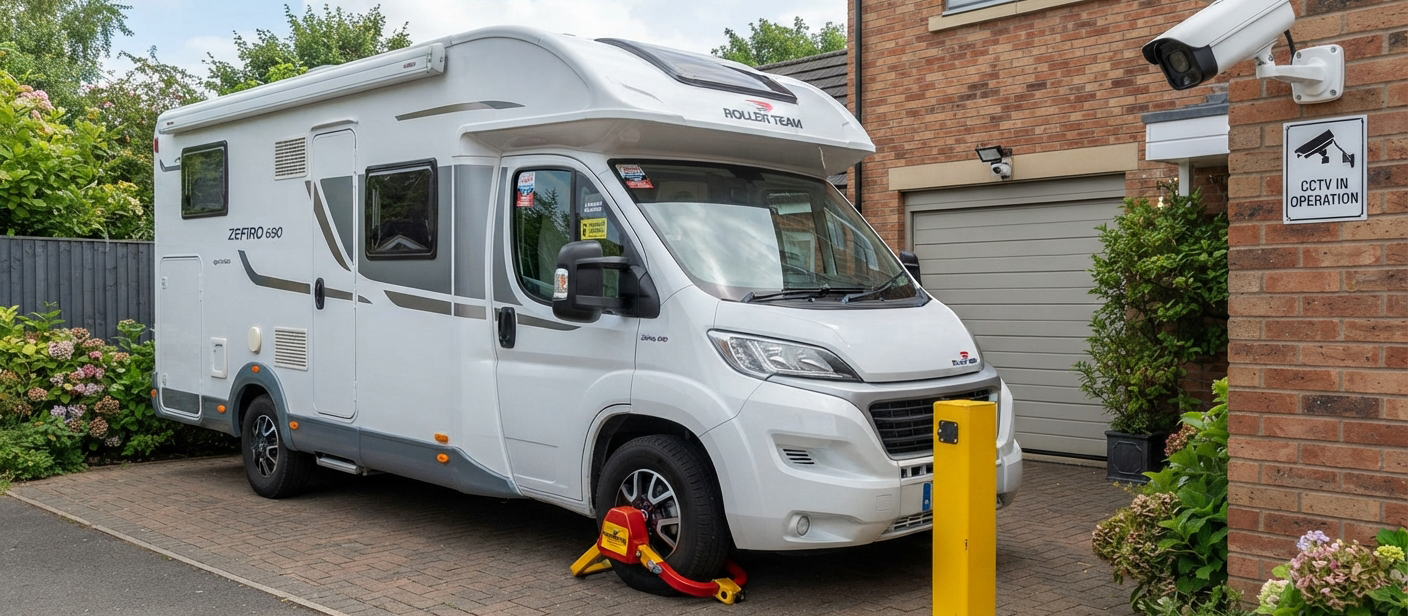
The Strategy: Invest in extra security and make sure your broker knows about them. Key additions include:
- Upgraded alarms and immobilisers.
- Thatcham-approved trackers (frequently required by insurers for higher-value vans).
- Heavy-duty driveway posts
- Security cameras covering your driveway or storage pitch.
- Wheel clamps – especially well known makes
- Steering wheel clamps
Saving tips
Seven ways to save
Compare like for like
Add a named driver
Set realistic mileage
Value it correctly
Review add-ons
Keep evidence ready
Check the fine print
Never assume a packaged bank-account policy covers your motorhome. Confirm the exact size limits and recovery terms before you travel.
Important
Security can support your quote
Approved Tracker
Approved Alarm
Steering Wheel Lock
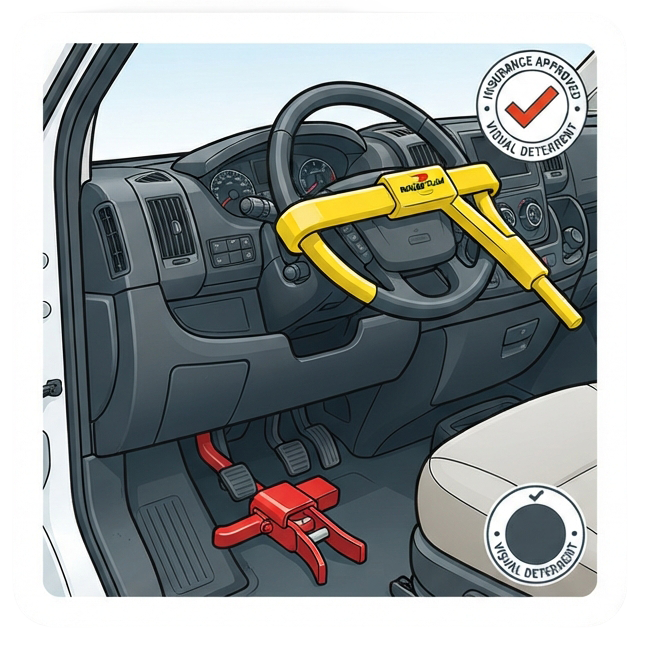
Wheel Lock